New York vs Miami Real Estate: What Buyers Should Know in 2026
By COSMORE Real Estate Group | Updated October 12, 2026
Miami continues to attract buyers drawn to waterfront living, business opportunities and Florida’s tax environment. Manhattan, meanwhile, is recording strong sales despite higher borrowing costs and new questions around second-home ownership.
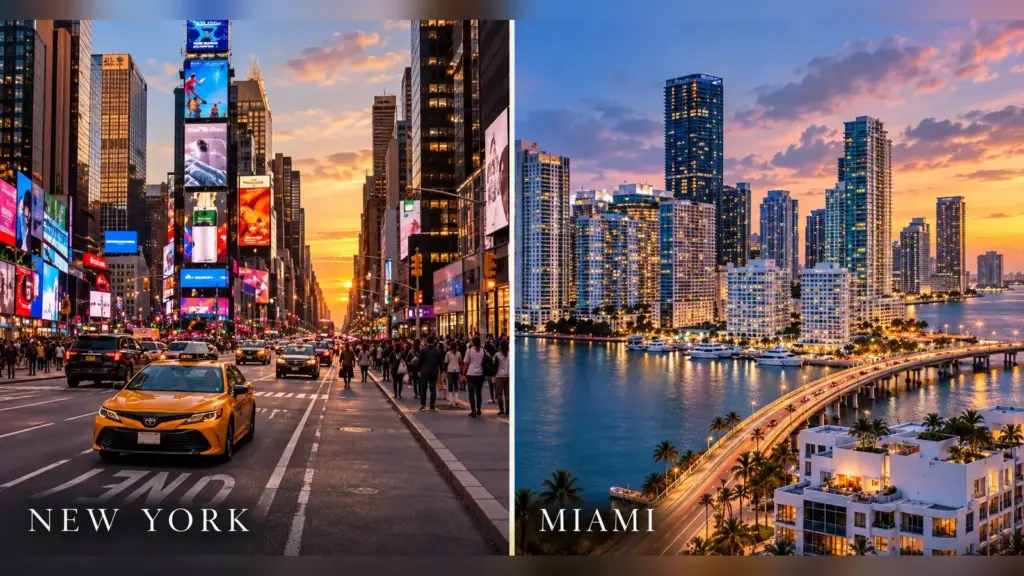
For anyone comparing New York vs Miami real estate, the useful question is how each market fits their plans—and what owning a property will actually cost.
The latest figures offer a more balanced picture than the familiar story of everyone leaving New York.
What the migration numbers actually show
The latest available IRS migration data, covering filing years 2022–2023, recorded 43,187 tax returns moving from New York State to Florida, compared with 22,011 moving in the opposite direction.
Those heading to Florida reported approximately $5.75 billion in adjusted gross income, versus $1.98 billion for those heading to New York.
These are statewide figures based on changes in tax-return addresses. They provide useful context, but do not measure moves specifically between Manhattan and Miami—or the amount of money invested in property. The clear takeaway is that movement runs in both directions, with a larger southbound flow in that period. (IRS)
Miami: strong luxury demand, different conditions across the market
Miami’s high-end market remains active. According to MIAMI REALTORS® + RWorld, Miami-Dade recorded 194 home sales of $10 million or more through August 2026, already exceeding its full-year 2025 total.
Cash purchases represented 37.8% of all Miami-Dade residential closings in August and 50.5% of existing condo sales. Yet overall home sales fell 1.1% year over year that month, underscoring why luxury headlines should not be treated as a description of every property. (MIAMI REALTORS®)
For condo buyers, the building deserves as much attention as the apartment.
Florida’s inspection and structural reserve requirements, including subsequent legislative changes, make it essential to understand the association’s financial position and planned work. Review applicable milestone inspections, the Structural Integrity Reserve Study, budgets, insurance coverage and approved or anticipated assessments. (Florida Senate)
A lower asking price can be attractive, but substantial upcoming expenses may change the calculation. Likewise, newer construction should still receive a thorough financial and technical review.
Manhattan: strong closings, a more measured outlook
Manhattan’s third-quarter results challenge the idea that New York has lost its appeal.
Corcoran reported 3,625 closed sales in Q3 2026, up 9% year over year, and a median sale price of $1.25 million, a third-quarter record. Active listings fell 3% to 6,354.
However, signed contracts declined 6% over the same period. Strong completed sales and softer contract activity can coexist: they describe different stages of the market. (Corcoran)
For buyers, this supports a selective approach. Compare recent transactions in the specific building, monthly ownership costs and the property’s condition. If considering a co-op, investigate financial requirements, board approval and restrictions on subletting or use as a second home before committing.
For sellers, market-wide strength still needs to translate into a realistic asking price for the individual property.
Moving from New York to Miami: look beyond income tax
Florida does not impose a personal income tax, which can make relocation financially attractive. But buying a Miami home does not automatically end New York tax residency, and working remotely from Florida can still leave some employment income subject to New York State tax. (Florida Department of Revenue, NYS Department of Taxation)
Keeping a New York apartment also requires careful planning. NYC introduced an annual surcharge in 2026 on certain high-value properties that are not used as a primary residence. Applicability depends on the property type, Department of Finance valuation and exemptions—not simply the purchase price. (NYC Department of Finance)
Our guide to NYC’s pied-à-terre tax explains the issue in more detail.
Before choosing either market, compare:
- Total ownership costs: financing, property taxes, insurance, association charges and potential assessments.
- Intended use: primary home, occasional residence or rental investment.
- Flexibility: building rules, leasing restrictions and the ability to sell when your plans change.
For an investment property, assess income after expenses, vacancy and maintenance reserves. For a home, consider everyday practicalities such as commuting, travel and access to the places you use most.
One decision, with both markets in view
Relocating, buying a second home and investing each call for a different property strategy.
With teams in Miami and New York, COSMORE helps buyers and sellers compare neighborhoods, evaluate properties and coordinate their next move across both markets.
Speak with COSMORE about your plans.
This article provides general information. Tax treatment and property obligations depend on individual circumstances and should be reviewed with qualified advisors.
More to read
How Much Do NYC Real Estate Agents Make in 2026?
Read article
NYC Pied-à-Terre Tax 2026: Who Pays, Rates and Next Steps
Read article