Real Estate Market Fluctuations in Recent American History
The honeycomb theory is a valid representation of an economic and social phenomenon. Recent history has observed it repeatedly in the real estate market of the last 50 years. Prices go up and down in the short term. However, the trend is always ascending in the medium and long term. There have been few notable exceptions, and we will briefly analyze their characteristics below.
Two decades of price data
Let’s start from the beginning of the ‘80s. The official data provided by the FHFA1 show the trend of average prices of real estate transactions over two periods. The two graphs below cover 1980 to 2000 (Graph 1) and 2001 to 2021 (Graph 2).
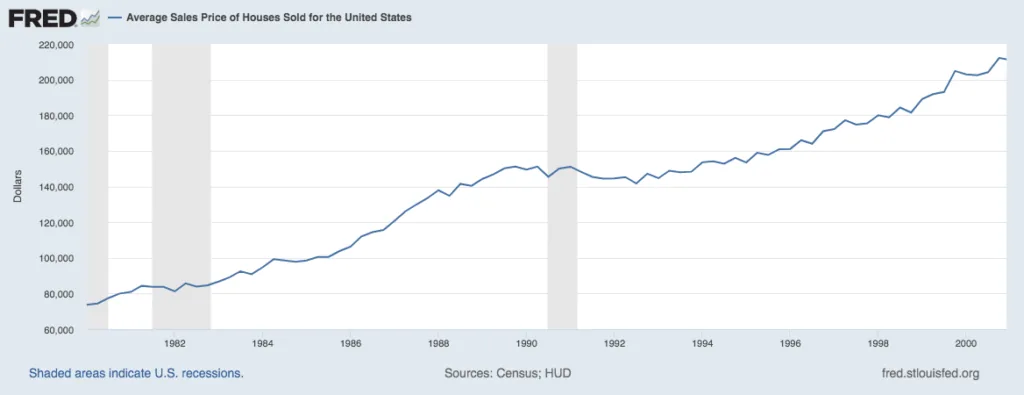
(Chart 1) Average prices trend of real estate transactions in the United States from 1980 to 2000.
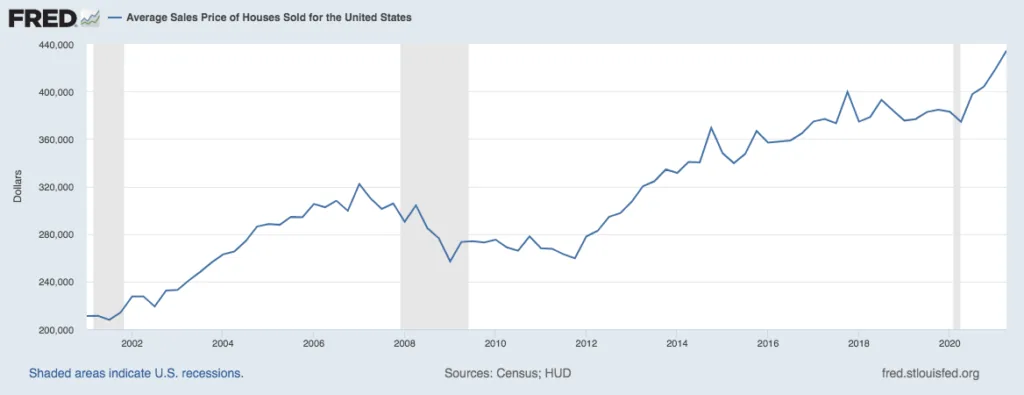
(Chart 2) Average prices trend of real estate transactions in the United States from 2001 to 2021.
It is immediately evident that the short term is characterized by continuous fluctuations. Increases and decreases in sale prices follow one another and alternate. However, the general trend is positive in the medium and long term.
The five-year period 94-99 gives a visually immediate idea. In fact, no unexpected and relevant external events influenced the market in those years. Therefore, it seems evident that, under stable conditions, this is the normal behavior of the real estate market.
What we observe confirms that general growth of the economy always corresponds to growth in real estate. However, there are continuous and seemingly inevitable “ups and downs”, which point to an upward trend.
Two exceptions to the trend
Two obvious exceptions to this upward trend occurred. The first happened between 1989 and 1992. Then came the second, of remarkable magnitude, between 2007 and 2014.
The first phase of market stagnation, although brief, coincided with the most intense period of the Savings and Loan Crisis (S&L Crisis). In this crisis, more than 1,000 savings companies failed between 1986 and 1995. That is about one-third of the total in the United States.
The crisis had a number of causes. These included regulations that were inadequate for market conditions, speculation, and moral hazard caused by taxpayer guarantees combined with deregulation. In addition, there were rampant corruption and fraud. Finally, greatly relaxed and expanded lending standards led banks to take on too much risk, balanced by too little capital on hand.
All these factors contributed to the recession of 1990-1991. As we see in the chart above, the real estate market temporarily halted its climb at that time.
In the same years, the Gulf War took shape. Its major events took place between 1990 and 1991. As a result, investors and consumers felt further uncertainty.
This was undoubtedly a particular period in history. Elements unrelated to the real estate market heavily influenced the economy at large.
The U.S. Housing Bubble
Something similar, and far worse, happened between 2007 and 2012, with its aftermath until 2014. It is now known as the U.S. Housing Bubble, followed by the Great Recession.
The events of 2007 are very recent history and probably familiar to readers in every industry. To simplify, we can limit ourselves to recalling one fact. At the beginning of the 2000s, it became very common in the United States for consumers and banks to agree on mortgages without home equity. In other words, the mortgages were above the value of the property.
Some banks used to lend at 120% or more. In this way, the buyer could buy the house and then pay for renovations or other expenses. Initially, this practice generated a wave of real estate purchases and great enthusiasm among investors and families. However, after a certain period of time, they came up against serious inflation and the difficulty of meeting debt repayments.
At the same time, the market experienced a downturn in prices. Moreover, the average wages of American families did not rise enough to offset inflation and stop the crisis.
Why debtors chose foreclosure
In such a scenario, a savvy investor or consumer would normally try to sell the property at the best possible price. In this way, they could cover the mortgage and preserve their equity.
But at that particular time, a great many debtors had no equity at all. Selling through traditional channels would have resulted only in additional costs: commissions, closing costs, and the balance owed to the bank in addition to the value of the property. In other words, the debtors did not see a sale on the traditional market as a possible salvation. So the vast majority quietly decided to let the properties go into foreclosure, knowing that it would be the most painless option for them.
The huge amount of foreclosed properties further depressed an already ailing market. As a result, prices plummeted and the supply of real estate far exceeded demand. Moreover, increasingly restrictive bank policies and the recession compromised demand even further.
This scenario is unique in recent history. It occurred at that precise moment because of the extreme flexibility, and greed, with which some banks had regulated their credit policies.
There were only two exceptions. One was brief and concentrated in the sector (1990-1992). The other was long and widespread throughout the economy (2007-2012). Apart from these two cases, the two decades of the real estate market have confirmed the rule of repeated oscillations with a constant upward trend.
1 The Federal Housing Finance Agency (FHFA) was established by the Housing and Economic Recovery Act of 2008 (HERA) and is responsible for the effective supervision, regulation, and housing mission oversight of Fannie Mae, Freddie Mac (the Enterprises) and the Federal Home Loan Bank System, which includes the 11 Federal Home Loan Banks (FHLBanks) and the Office of Finance. Since 2008, FHFA has also served as conservator of Fannie Mae and Freddie Mac.
More to read
Moving From New York to Miami in 2026: Taxes, Domicile and What to Do With Your NYC Home
Read article
Buying a Condo in Miami: SIRS and Milestone Checklist
Read article